

5.0 from 78 Reviews
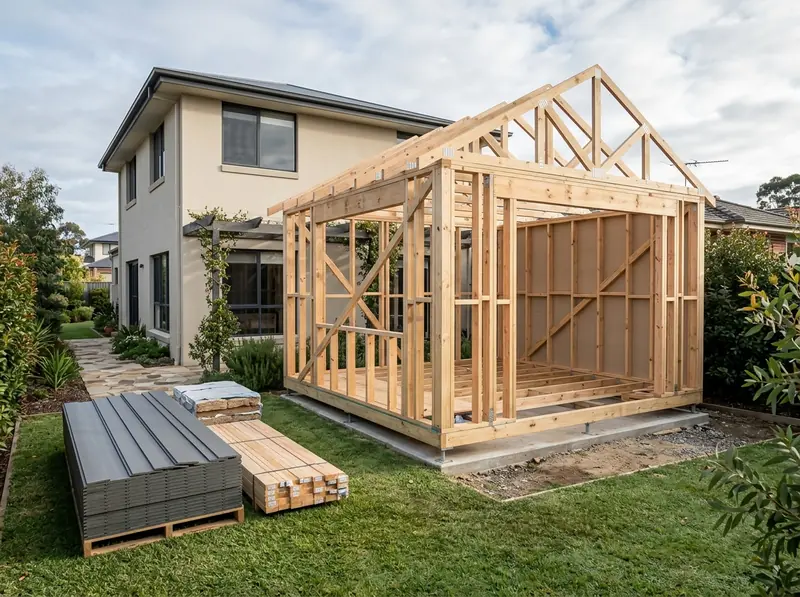
Building a granny flat is one of the most practical ways to add value to your property, generate rental income, or create space for family. But funding the build is a step that many homeowners are unsure about. That is where construction loans for granny flats come in.
At Granny Flat Loans, we specialise in helping Australians across the country find the right finance to get their granny flat off the ground. A construction loan is specifically structured for building projects. Rather than receiving a lump sum upfront, funds are released in stages as your build progresses. This means you only pay interest on the money that has been drawn down at any given time, which can help manage your cash flow during the construction period.
Construction loans for granny flats are different from standard home loans, and not every lender handles them the same way. Some lenders are comfortable with granny flat builds, while others apply restrictions based on property type, location, or how the dwelling will be used. That is why working with a specialist broker matters. At Granny Flat Loans, we know which lenders are well-suited to granny flat construction finance and how to present your application in the strongest possible way.
Whether you are an owner-occupier looking to house a family member, or an investor wanting to boost your rental yield, construction loans for granny flats can be structured to suit your situation. The loan amount, repayment structure, and lending criteria will all depend on your individual circumstances, including your existing mortgage, your equity position, and the projected value of your property once the build is complete.
If you already have a mortgage on your property, there are several ways to approach granny flat construction finance. You may be able to access the equity you have built up in your home, refinance to fund a granny flat, or look at a split loan arrangement that keeps your construction borrowing separate from your existing home loan. Granny Flat Loans works through these options with you to find a structure that fits.
For investors, construction loans for granny flats open up the possibility of creating a second income stream on a single title. Lenders assess these applications differently depending on whether the granny flat will be rented separately, used for NDIS housing, or occupied by a family member. Understanding how rental income is treated by different lenders is a key part of getting your finance approved, and it is something Granny Flat Loans handles on your behalf.
Location also plays a role. Some lenders apply postcode restrictions or have different policies for rural and regional properties. If your property is outside a major metro area, it is important to work with a broker who understands granny flat loans on acreage and rural properties and knows which lenders will look at your situation favourably.
Construction loans for granny flats require a fixed-price building contract, council-approved plans, and a licensed builder before most lenders will proceed. Granny Flat Loans can help you understand what documentation is needed so you are prepared when the time comes to apply.
No matter your circumstances, Granny Flat Loans is here to help you find a construction loan that works for your granny flat project. We work with a broad panel of lenders across Australia and take the time to understand your goals before recommending a lending solution.
Contact Us
Have questions about construction loans for granny flats? Get in touch with the team at Granny Flat Loans today. We are here to help you understand your options and find a lending solution that suits your build.
Initial Consultation
Your journey begins with a conversation about your property goals - whether you're purchasing a home, investing, refinancing, or seeking another type of loan. Our Finance & Mortgage Brokers explain the overall loan application process, assess your financial position, and begin identifying suitable loan options from a wide panel of banks and lenders across Australia.
Financial Assessment
Your broker conducts a detailed review of your finances, including income, expenses, assets, liabilities and savings. They determine your borrowing capacity and explain key terms like loan-to-value ratio (LVR), lenders mortgage insurance (LMI), and any government schemes or discounts you may be eligible for.
Loan Comparison & Selection
With a clear understanding of your financial situation, our Finance & Mortgage Brokers research and compare a range of loan options. These may include fixed or variable interest rate loans, products with offset accounts, or flexible repayment features. Our brokers help you weigh the pros and cons of each loan, ensuring you choose the one that aligns best with your needs and preferences.
Loan Pre-Approval
Securing loan pre-approval provides a clear idea of how much you can borrow and strengthens your position in the property market. Your broker prepares and submits the required documents - such as payslips, tax returns, and bank statements - to the lender for assessment. Pre-approval also gives you confidence to make offers when you find the right property.
Formal Loan Application
Once you've chosen your preferred loan, your broker completes and submits the formal application to the lender. They manage all required documentation, respond to any queries from the lender, and keep you informed throughout the process to avoid unnecessary delays.
Loan Approval & Settlement Preparation
After your loan is formally approved, our brokers review the loan agreement with you and confirm that all terms - such as interest rate, fees, and repayment schedule - are clear and understood. They also help you set up your loan account and arrange any necessary insurance, such as mortgage or home loan protection.
Settlement & Ongoing Support
At settlement, the lender advances the funds and ownership of the property is transferred to you. Our brokers coordinate with your solicitor or conveyancer to ensure everything runs smoothly. After settlement, our Finance & Mortgage Brokers remain available for ongoing support - whether it's managing repayments, exploring refinancing opportunities, or helping with future property plans.
How we can help
Granny Flat Loans is a specialist mortgage broker focused entirely on granny flat finance. We understand the nuances of construction loans for granny flats in a way that general brokers often do not. From understanding how lenders assess dual-occupancy properties to knowing which banks will count projected rental income in your borrowing capacity, our knowledge is specific and practical.
We work with clients Australia-wide, helping owner-occupiers, investors, retirees, and multigenerational families access granny flat construction finance suited to their needs. Our role is to match you with the right lender, prepare a strong application, and guide you through the process from start to finish. We also help clients who need to access equity release to build a granny flat or who are exploring a split loan for granny flat construction to keep their finances organised during the build.
At Granny Flat Loans, we believe that getting the right finance should not be complicated. We take the time to explain your options clearly, so you can make informed decisions with confidence.
What Our Clients Say
Nick and the team were so lovely. Professional, genuine, responsive and easy to deal with. Would highly recommend.
Thea Edwards
Nick and the team were a pleasure to work with. They answered all of my questions and if they weren't immediately available, they were always quick to call me back.
simon preshaw
As a founder, getting a mortgage requires a couple more hoops to jump through, which is why I couldn't recommend Nick O'Sullivan and the Azura team more highly. Not only were they able to offer a seamless process, but Nick was also patient with us as we changed our minds about when to buy (over a period of years!). The truth is anyone can approach a bank and get a mortgage, but when things don't go perfectly (e.g. abrupt government changes), that's when you want a pro on your team like Nick.
Shaun Cunningham
Frequently Asked Questions
Going directly to a single bank means you are limited to that lender's products and policies, which may not be the most suitable option for your situation. A mortgage broker like Granny Flat Loans has access to a panel of lenders, which means we can look across multiple options and find one that aligns with your needs and circumstances. Granny flat finance can be more involved than a standard home loan, and not all lenders approach it the same way. Having someone in your corner who understands the specific requirements of this type of lending can make a real difference. We take the time to understand your goals, explain your options clearly, and manage the process with you from start to finish. There is no obligation to proceed, and we are always happy to have an initial conversation.
The documents required for a granny flat loan application are similar to those needed for most home loan applications, though there may be additional requirements depending on the nature of the project. Generally, you can expect to need proof of income such as recent payslips or tax returns, bank statements, identification, and details about the property involved. If you are looking at a construction loan, you will also likely need council-approved plans, a fixed-price building contract, and details about the builder you intend to use. Our team at Granny Flat Loans will walk you through exactly what is needed based on your specific situation and the lenders we are looking at for you. Being prepared with the right documents from the start can help avoid unnecessary delays.
Many property owners do choose to rent out their granny flat, and potential rental income can be a factor that lenders take into account when assessing a loan application. However, how lenders treat rental income varies, and not all lenders will factor it in the same way. There are also tax and legal considerations that come with renting out a secondary dwelling, including landlord obligations, tenancy laws, and potential impacts on your tax position. These are matters you would want to discuss with a qualified accountant or legal professional. From a finance perspective, our team at Granny Flat Loans can help you understand how rental income may be viewed by lenders and how it could factor into your overall borrowing position.
Council approval requirements vary depending on your state or territory and the specific local government area your property falls under. In some cases, you may be able to begin the finance application process before council approval is finalised, but lenders will typically want to see that the project is viable and that approvals are either in place or well underway before releasing funds. It is important not to get too far ahead with construction plans before understanding both the council requirements and the finance side of things. Our brokers can help you understand what lenders generally expect in terms of approvals and documentation. We recommend speaking with your local council or a town planner alongside working with us so that both sides of the process move forward together.
The timeframe for a granny flat loan application can vary depending on a number of things, including the complexity of your financial situation, the lender chosen, and how quickly all the required documentation is gathered and submitted. Some applications move through relatively quickly, while others may take longer if there are additional checks or conditions involved. Construction loans, in particular, can have more steps involved compared to a standard loan, as funds are often released in stages as the build progresses. Our team works to keep things moving as efficiently as possible and will keep you informed throughout the process. We will also let you know upfront what documents and information you are likely to need so there are no unnecessary delays on your end.
A granny flat loan is not always a separate product on its own. In many cases, it involves restructuring or extending an existing home loan, accessing a construction loan, or using a line of credit secured against your property. The key difference from a standard home loan is the purpose of the funds and how the lending is structured to account for the secondary dwelling being built or purchased. Lenders assess these applications with additional considerations in mind, such as council approvals, construction timelines, and the impact on the property's overall value. Because of these differences, it is important to work with someone who understands granny flat finance specifically. That is exactly what our team at Granny Flat Loans is here to help with.
Eligibility for granny flat finance can depend on a number of factors, including the type of property, its location, the size of the land, and local council regulations. Generally speaking, granny flats are built on residential properties where there is enough space to accommodate a secondary dwelling. Lenders will also consider the overall value of the property and how the addition of a granny flat may affect that. Properties in metropolitan and regional areas across Australia can be considered, though requirements may differ between states and territories. At Granny Flat Loans, we work with clients from all over Australia and understand that every property situation is different. We will help you understand what lenders are likely to look for when assessing your application.
Yes, many Australians build granny flats specifically to house ageing parents, adult children, or other family members. It is one of the most common reasons people look into this type of finance. Having a family member close by can provide peace of mind, reduce living costs, and support family connections, all while making use of existing land. When it comes to financing a granny flat for a family member, lenders will still assess the loan based on your financial position and the property involved. It is worth understanding the legal and council requirements in your state or territory as well, as these can vary. Our brokers can help you understand the finance side of things and point you in the right direction for other considerations.
Having equity in your existing property is one common way to access finance for a granny flat, but it is not always a requirement. There are different ways lenders can structure granny flat finance, and the right approach depends on your individual financial situation. Some borrowers use the equity they have built up in their home as security, while others may look at construction loans or other lending options. The key is understanding what is available to you based on your income, assets, and overall financial position. Our team at Granny Flat Loans will take the time to understand your circumstances and help you explore what options may be available to you through our panel of lenders.
A granny flat loan is a type of finance used to fund the construction or purchase of a secondary dwelling on a residential property. These smaller, self-contained homes are built on the same block as the main residence and are commonly used to house family members, generate rental income, or add value to a property. The loan works by using the equity in your existing property or by structuring a new finance arrangement to cover the cost of the build or purchase. At Granny Flat Loans, we work with a wide range of lenders to find a finance option that suits your situation. Every application is assessed individually, so the structure of your loan will depend on your personal circumstances, the property involved, and the lender's requirements.
Ready to Take the First Step?
If you are ready to explore construction loans for granny flats, the team at Granny Flat Loans is here to help. Book an appointment today and let us find a lending solution that suits your property and your goals.
Latest Articles
Stay informed with the latest insights on granny flat finance, construction loans, and property investment from the Granny Flat Loans team.


